How a bigger payout may come with a catch


Geared credit can lift an investor’s income. But before an investor takes the plunge, they should understand a geared ETF’s mechanics as well as its opportunities and risks.
For years, low interest rates forced Australian investors seeking income up the risk curve, including investing in shares that pay high dividends.
But the recent surge in bond yields, alongside changes to capital gains tax arrangements announced in the 2026 Federal Budget, has renewed interest in what bonds and bond ETFs can offer.
The good news is that higher bond yields have expanded investors’ income opportunities. But choosing a fund by its headline yield alone can mean overlooking how that income is generated. For example, some funds that promote their yield are geared. They may look like a high-grade bond fund, but underneath is a leveraged position funded by short-term borrowing.
There could be a risk that investors may be less familiar than those associated with shares, bonds and term deposits.
Why income is getting another look
Firstly, let’s have a look why income investing is coming back to the fore. The surge in bond yields to two-decade highs has been spurred on by persistent inflation and geopolitical uncertainty. The Reserve Bank of Australia has raised the cash rate four times to 4.60%, and markets have not ruled out a fifth hike before the end of the calendar year. Other central banks such as the US Federal Reserve have also raised rates lately.
Higher rates can support income from fixed income, and at these levels, fixed income funds can generate greater payments than other investment options. At current levels, this is higher or comparable with high dividend shares, but with a perceived less level of risk, because bonds are traditionally associated with less risk.
Bond funds are attracting investor interest, but not all bond funds generate their income in the same way. Some rely on the interest earned from bonds bought with investors’ money while others add borrowed money to buy more bonds, increasing the income potential of the portfolio. This approach is known as geared credit.
How borrowed money becomes bond income
First, let us recap how fixed income investing works. Investors lend money to borrowers, such as governments and companies, in exchange for interest and repayment of the bond’s face value at maturity (should they hold on that long). As we’ve mentioned before, those payments depend on the borrower’s ability to meet its obligations.
A geared credit fund takes this concept one step further by combining investors’ money with borrowing to buy a larger portfolio than investors’ money alone could purchase.
For example, a fund combines $100 from investors with $200 of borrowing to buy $300 of bonds. Assuming the bonds earn 5.6% a year and borrowing costs 4.8%, this leaves investors with $7.20 in annual income, compared with $5.60 without borrowing, before fees and other expenses. The chart below shows the calculation.
Chart: How borrowing can boost bond income
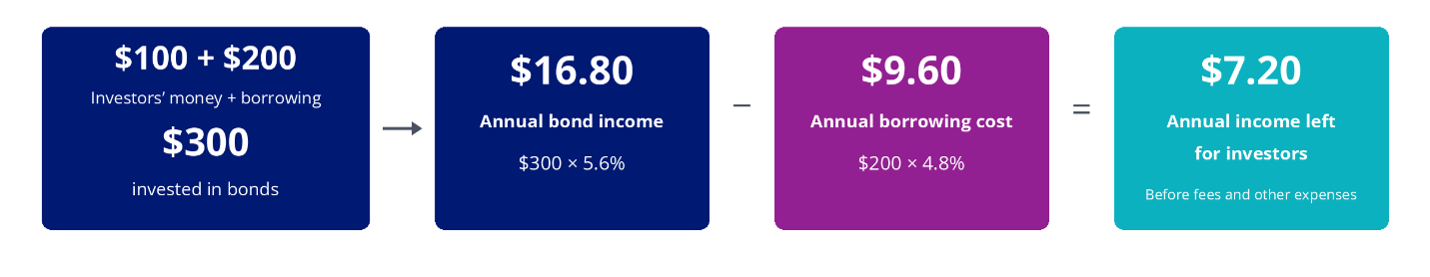
Source: VanEck. For illustrative purposes only. Assumes constant rates and balances over one year. Excludes management fees, other expenses, tax and changes in bond values. This is not an actual fund return or a forecast.
One thing to note is that the borrowing happens inside the fund. That means the manager arranges the finance, which may involve bank loans or funding secured against the portfolio’s bonds, and the manager uses the proceeds to increase its investments. While this makes gearing accessible because it means investors don’t have to arrange a loan themselves, the borrowing costs and amplified gains or losses still flow through to their investment.
The bonds can fall without a default
Bond prices can fall without a borrower missing a payment. For fixed-rate bonds, rising market interest rates can reduce bond prices. Floating-rate bonds have much less sensitivity to those movements because their interest payments adjust as benchmark rates change.
Both remain exposed to credit spreads, the extra yield above a benchmark rate that compensates investors for credit risk.
If investors demand more compensation for the risks they are taking, spreads widen and existing bond prices generally fall. For floating rate credit funds, this can be a more significant source of price risk than changes in market interest rates. Gearing magnifies those price movements.
Return to our example, where $100 of investors’ money and $200 of borrowing bought $300 of bonds. A 3% fall in bond prices wipes $9 off the portfolio’s value without reducing the debt that the fund owes.
Chart: How borrowing can magnify bond losses
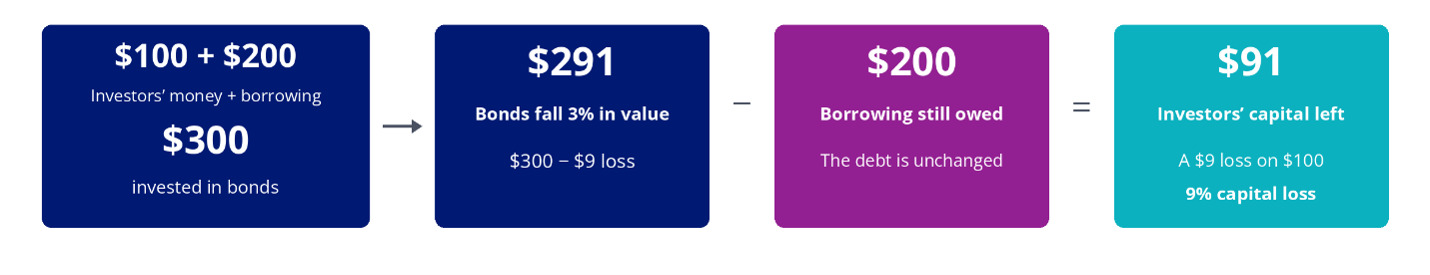
Source: VanEck. For illustrative purposes only. Assumes an immediate, uniform price decline, with no portfolio transactions or change in borrowing. Excludes income, borrowing costs, management fees, other expenses and tax. This is not an actual fund return or a forecast. Gearing magnifies gains and losses.
More than a question of yield
There are other risks associated with gearing in fixed income.
For instance, if bond prices fall, the fund may need to sell some holdings to keep its borrowing within permitted limits. This can lock in losses and leave less invested when markets recover.
The fund may also need to renew its loans at regular intervals. If lenders charge more, demand additional security or reduce their lending, the fund could face higher costs or be forced to sell bonds to repay some of its debt.
And on the subject of costs, some funds charge management fees on the entire portfolio, including bonds bought with borrowed money. Investors should check both what the fee covers and how it is calculated, because these costs reduce the extra income gearing can deliver.
Gearing can also reintroduce risks investors were hoping to reduce by moving into fixed income. Borrowing to increase income can make the investment more sensitive to market falls and funding conditions, potentially undermining the stability investors sought in the first place.
All these factors can affect both the value of the investment, and the distributions investors receive.
Make the comparison count
Taking more risk does not guarantee more income.
We believe investors should understand what generates their income payments, what could affect them and what risks they are taking with their capital.
That principle underpins VanEck Australia’s extensive fixed income range, spanning index-tracking funds and specialised active strategies.
None of VanEck’s fixed income ETFs borrow to boost income. Each has its own risks, giving investors different ways to pursue income according to their needs and circumstances.
A higher yield deserves consideration. So does the risk taken to earn it.
Published: 27 October 2026
Any views expressed are opinions of the author at the time of writing and is not a recommendation to act.
VanEck Investments Limited (ACN 146 596 116 AFSL 416755) (VanEck) is the issuer and responsible entity of all VanEck exchange traded funds (Funds) trading on the ASX. This information is general in nature and not personal advice, it does not take into account any person’s financial objectives, situation or needs. The product disclosure statement (PDS) and the target market determination (TMD) for all Funds are available at vaneck.com.au. You should consider whether or not an investment in any Fund is appropriate for you. Investments in a Fund involve risks associated with financial markets. These risks vary depending on a Fund’s investment objective. Refer to the applicable PDS and TMD for more details on risks. Investment returns and capital are not guaranteed.